

Till: Debit Card for Kids

- 318.00 Reviews
- 4.5
- Downloads
- 100,000+
Our take on Till: Debit Card for Kids from Appgk
Teaching a child to manage money is much easier when the lesson connects to something they can use in daily life. Till: Debit Card for Kids is built around that idea: it combines a debit card with a finance app intended to help children and teenagers become more thoughtful spenders. I approached it less like a banking product for adults and more like a family tool that needs to work smoothly during ordinary moments, such as buying lunch, saving for a personal goal, or checking whether a purchase fits within an agreed plan.
My overall impression is that Till is most useful when parents want a visible, guided way to introduce spending habits without handing over complete financial independence immediately. It is a free finance app from Till Financial, rated for Everyone, with optional in-app purchases ranging from $7.99 to $79.00 per item. The app has built a solid audience, with an average rating of 4.5 from around 2.2 thousand ratings and more than 100 thousand installs.
That popularity does not make setup friction disappear, though. A family finance app has more moving parts than a simple budgeting calculator: an adult may be creating access, a child may be using a card, and both sides need to understand what is happening. My review therefore focuses on the moments when people are likely to get stuck, the checks that can prevent avoidable problems, and the situations where the issue may be outside the app itself.
Where families are most likely to get stuck
The first-use experience needs patience
The hardest part of using a child-focused money app is rarely tapping through screens. It is deciding how the family will use the product. Before opening Till, I would agree on a few basics: what the child is responsible for, how spending decisions will be discussed, and whether the card is meant for regular purchases, a limited allowance, or a specific purpose. Without that conversation, even a well-designed tool can feel confusing because the app is being asked to solve a family agreement that has not yet been made.
Best Parts of Till: Debit Card for Kids
Things to Keep in Mind About Till: Debit Card for Kids
I also found that the adult should stay involved during the initial setup rather than treating it as something the child can complete alone. The product is designed around a child or teenager using a debit card while growing into better spending habits, so the parent’s role matters. If the wrong person starts the process, or if the family changes its plan halfway through, the resulting confusion may look like an app problem when it is really a setup decision.
Another common sticking point is expectation management. Till is not simply a digital version of a cash envelope, and it is not intended to replace every feature of a full adult bank account. Its value comes from making money use more visible and teachable for younger users. Families looking for advanced adult banking, complex investing, or a broad financial dashboard should not assume that a child-oriented product will provide those things.
News and Features Related to Till: Debit Card for Kids

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Card use can expose misunderstandings quickly
When a child tries to pay for something and the experience does not go as expected, the natural reaction is to blame the app. In practice, several ordinary details can be involved: the available balance, the purchase amount, the merchant’s payment process, or whether the card is being used in a way the family did not anticipate. A calm check of each part is more useful than repeatedly tapping buttons.
I recommend that parents and children review a small purchase together before relying on the card for an important outing. That first transaction can teach the child where to look, how to think about the remaining money, and how to report a problem. It also gives the adult a chance to notice whether the family’s rules are clear enough. This is one of Till’s strongest educational opportunities: the card turns an abstract conversation about money into a concrete decision.
Don't want to read the full review?
The trade-off is that visibility can create more questions. A child may ask why a purchase appears differently from what they expected, while a parent may need to explain that a card transaction is not always as simple as handing over cash. I see that as useful learning, but it does require an adult who is willing to coach rather than merely monitor.
Notifications and transaction timing can feel confusing
People often expect a finance app to show every event instantly and in exactly the same form as the receipt. That is not always how payment systems behave. A purchase can involve the merchant, the card network, and the account display, so a delay or a different-looking entry does not automatically mean money has vanished or that the card is broken.
Screenshots
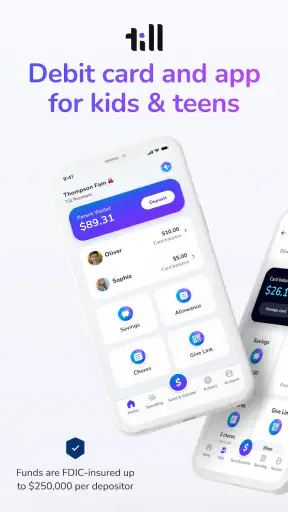
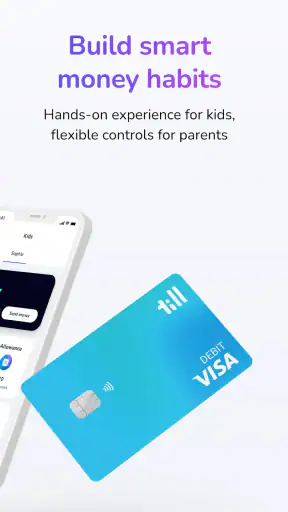
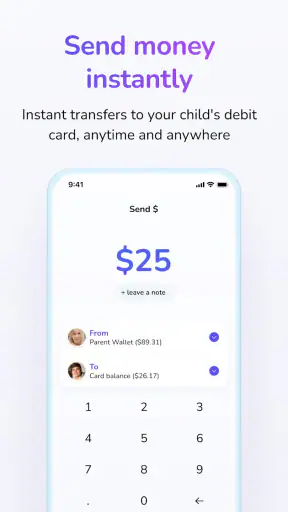
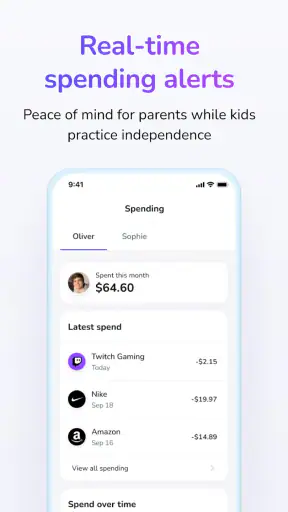
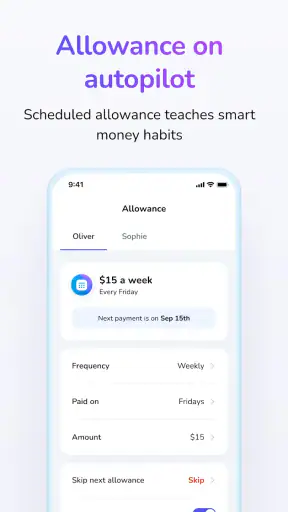
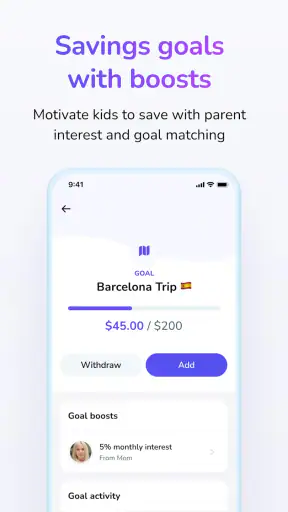
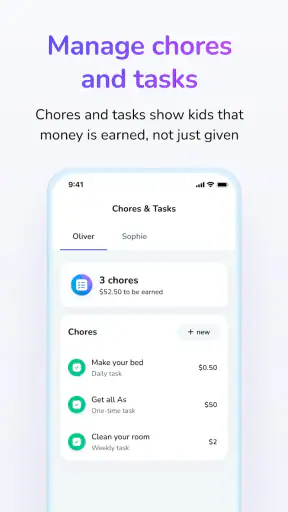
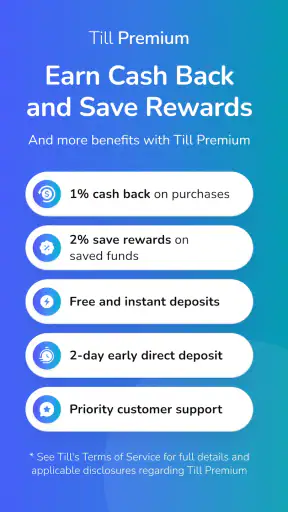
My practical advice is to compare three things before taking action: the receipt, the amount the child remembers approving, and the transaction shown in Till. If they do not line up, avoid making a second purchase simply because the first one is not visually clear yet. Write down the time, merchant, and amount, then check again later. This simple habit is valuable for both troubleshooting and financial education.
In-app purchases deserve attention
The app itself is free to install, but optional in-app purchases are listed from $7.99 to $79.00 per item. That makes it important for an adult to review purchase expectations before a child begins using the product. I would not assume that “free” means every part of the experience has no cost. Families should discuss who is allowed to approve an optional purchase and whether it fits the household budget.
This is also a useful moment to teach the difference between using a financial tool and buying an add-on inside one. A child may understand that a card purchase costs money but not realize that an in-app purchase can also affect the family’s spending. Keeping those conversations separate makes the app easier to manage and avoids surprises.
Setup checks that prevent avoidable problems
Start with the correct adult and child roles
Before installing Till, I would decide which adult will take responsibility for the account and which child will use the card. That sounds obvious, but it prevents a surprisingly common kind of confusion: one person expects to control the experience while another person has actually begun the setup. A single, consistent starting point is easier to manage than several family members trying different paths.
Once the app is installed, read each screen carefully instead of rushing through it. Use the child’s details consistently, check every confirmation before moving on, and keep any relevant account information available. If a screen does not behave as expected, closing the app immediately is usually less helpful than noting what happened and returning to the previous step carefully.
Till runs on Android 7.0 or later, so an older Android device should be checked before installation. Compatibility is only one part of a smooth experience, but it is an easy one to verify. If the device is shared, I would also make sure the child knows which account or profile is being used, since switching between profiles can make a successful setup appear to have disappeared.
Prepare the phone before blaming the service
Basic device housekeeping can make a meaningful difference. I would confirm that the phone has a stable internet connection, enough free storage for normal app operation, and a current enough operating system for the app. If the screen is frozen, I would first close and reopen Till, then restart the device if needed. These are simple steps, but they distinguish a temporary phone issue from a genuine account or card issue.
The current version is 162.41.0, so keeping the installed app current is sensible when an update is offered through the relevant app store. An update can resolve compatibility problems, but I would avoid uninstalling the app as a first response if I am not certain that I know the account details needed to sign in again. Recovery is easier when the family has kept those details organized.
I would also check whether the device is connected through a network that blocks or interrupts normal access. A child using public Wi-Fi, a weak mobile signal, or a family device with aggressive battery restrictions may experience loading problems that are not caused by Till’s account system. Moving to a reliable connection and trying again later can be more informative than repeating the same action immediately.
Make the money plan explicit before adding pressure
A useful setup is not just technical. I would write down the child’s spending rules in plain language: what the card is for, what requires a conversation first, and what happens when the available money is gone. The point is not to create a legal document. It is to prevent a child from guessing and a parent from changing expectations after a purchase.
For example, a family might decide that the card covers school-day spending but not large entertainment purchases. In that case, the child can practice making small decisions while still learning that some purchases need approval. This makes Till more effective than simply giving a child access to money with no structure.
Another helpful check is to test the workflow during a calm day, not five minutes before an important trip. Let the child open the app, locate the relevant balance or activity information, and explain what they would do if a purchase looked wrong. This rehearsal turns a stressful problem into a familiar routine.
Set expectations around optional costs
Because Till is free with optional purchases, I would review the purchase controls on the device and establish a family rule before handing the phone to a child. The exact household rule can vary, but the principle is consistent: a child should know whether an optional app purchase requires permission, and the adult should know where that permission is managed.
This check is especially important when the same device is used for games, entertainment, and finance. A child may not distinguish between an app add-on and a card transaction, while the adult may assume the child understands the difference. A short explanation at the beginning is much easier than sorting out an unexpected charge later.
Use the first week as an observation period
I would treat the first week as a learning period rather than immediately using Till for every purchase. Watch whether the child checks the app before spending, whether the family’s rules are realistic, and whether the adult can explain the activity without taking over. This reveals whether the tool is supporting independence or merely adding another screen to supervise.
One non-obvious benefit of this approach is that it separates financial behavior from technical behavior. If the child understands the balance but forgets the family rule, the next conversation is about judgment. If the child follows the rule but cannot find the information, the next step is about teaching the app’s workflow. That distinction helps families improve without unfairly blaming the product.
Recovering when a normal workflow breaks
When the app will not load correctly
If Till opens slowly, shows an incomplete screen, or fails to respond, I would work through a short sequence: check the connection, close and reopen the app, restart the phone, and confirm that the device still meets the Android requirement. If an update is available, install it and try again. I would avoid repeatedly entering information while the app is unstable, because that can create more uncertainty about what was actually submitted.
If the problem affects only one device, compare it with another trusted device if the family has one available and is comfortable doing so. If the same account behaves differently across devices, that points toward a device or connection issue. If the same problem follows the account, record the exact screen and action involved before seeking help. Clear notes make support conversations more productive.
When a card purchase does not look right
For a declined or unexpected card event, begin with the basics rather than assuming the account has been compromised. Check the available funds, confirm the purchase amount, and ask whether the merchant processed the payment more than once or used a temporary authorization. Keep the receipt and note whether the issue occurred in a shop, online, or at a terminal. The context matters when explaining what happened.
I would also teach the child not to keep retrying a payment without checking first. Multiple attempts can make the activity harder to understand, especially when the merchant’s terminal is slow. A better routine is to pause, tell the adult, and preserve the details. This is a practical habit that will remain useful even when the child eventually uses other financial products.
When information appears delayed
A delayed update can be frustrating because the child may be waiting to see how much money remains. In that situation, use the receipt and the child’s memory as temporary records, but do not treat them as a replacement for the account activity. Wait briefly, reopen the app once, and avoid making a new spending decision based on an assumed balance.
If the discrepancy remains, the adult should document the merchant, amount, and approximate time. The child can participate by describing exactly what they saw at the checkout. This keeps the response factual and reduces the chance that an anxious guess becomes part of the family’s explanation.
When sign-in or access becomes the obstacle
Access problems are easier to solve when the family has kept its account information in a secure, organized place. I would not create multiple new accounts simply because the first login fails. First check that the correct email or sign-in method is being used, that the device has a working connection, and that the app has not switched to a different phone profile.
If those checks do not help, use Till Financial’s official support route rather than relying on random advice from social media or entering sensitive information into an unofficial form. When contacting support, include the device type, Android version, app version, the step that failed, and any non-sensitive error wording. Do not share passwords, full card details, or security codes in a public discussion.
When Till is not the cause
Merchant systems can create misleading symptoms
Sometimes the app is blamed because the problem becomes visible after a card is used, even though the merchant’s terminal or checkout system is responsible. A payment terminal may be offline, a cashier may cancel and restart a transaction, or an online store may show a confusing confirmation page. Ask the merchant what happened and keep the receipt before concluding that the account is at fault.
This is where a child-focused card can become a teaching tool in an unexpected way. The child learns that a payment is a chain involving several systems, not a magic button that always produces an instant result. With an adult’s help, they can learn when to wait, when to ask the merchant, and when to report an account concern.
Device settings and connectivity deserve a fair test
A weak signal, restrictive battery setting, outdated device, or unstable network can interrupt a finance app just as easily as any other mobile app. If Till works at home but not during a trip, the connection is worth investigating. If it fails only after the phone has been idle, device power settings may be involved. I would test one change at a time so the family knows which adjustment helped.
Shared phones can add another layer of confusion. A child may open the app while the device is connected to a different account, or an adult may complete a step without realizing the child is watching a different screen. A clear habit of checking the active profile before troubleshooting prevents a lot of unnecessary resets.
Family expectations can be the real source of conflict
Not every disagreement about spending is a technical failure. A child may believe that having a card means every purchase is approved, while the parent may view it as a controlled learning tool. Till cannot replace the conversation that defines those boundaries. If the family has not agreed on the rules, the app may appear restrictive to the child or insufficiently flexible to the adult.
I would also be cautious about using Till as the only way to teach money. Cash, a simple written budget, or a conversation about needs and wants can still be valuable. The app is strongest when it gives those lessons a practical place to happen. It is less suitable when the family wants technology to make all financial decisions automatically or eliminate parental involvement.
Who should choose another type of tool
Till is a good match for parents who want a child or teenager to practice spending with guidance and a dedicated debit-card experience. It is less convincing for an adult who needs sophisticated budgeting, investment tracking, business finance, or a complete banking replacement. A traditional bank account may be better for mature teenagers who already understand money and need broader services, while a basic allowance method may suit younger children who are not ready for card-based spending.
It may also be the wrong choice for families that do not want to discuss transactions regularly. The educational value depends on involvement. If the adult wants a set-and-forget arrangement, the product’s child-development focus may feel like extra work rather than a benefit.
My practical verdict after using it as a family tool
I like Till because it treats a debit card as part of a learning process instead of presenting it only as a payment instrument. The most useful experience comes when the child checks before spending, thinks about the remaining money, and can explain a transaction afterward. That is more meaningful than simply receiving an allowance and never seeing the decisions behind it.
The main caution is that setup and troubleshooting require an adult to be organized. Families should confirm device compatibility, use a stable connection, keep roles clear, understand the difference between the free app and optional purchases, and test the workflow before depending on it away from home. When a payment looks wrong, checking the receipt, merchant, balance, and transaction timing prevents many rushed conclusions.
In an everyday scenario, I can see Till working well for a teenager preparing for a school outing. The parent and child agree on the spending limit and purpose, the teenager checks the app before buying lunch, and they review the transaction afterward. If something looks delayed, they keep the receipt and wait rather than retrying repeatedly. That small routine teaches planning, restraint, and problem-solving in a way that a lecture about saving rarely does.
My recommendation is therefore specific: choose Till if you want guided practice with a child or teenager and are prepared to stay involved during setup and early use. Skip it if you need adult-level financial tools, dislike supervising a young person’s spending, or want a completely hands-off allowance system. For the right family, Till: Debit Card for Kids offers a practical bridge between cash lessons and independent spending. Its best feature is not just the card; it is the opportunity to turn ordinary purchases into calm, repeatable conversations about money.
Till: Debit Card for Kids FAQ
What is Till: Debit Card for Kids, and who is it designed for?
Till is a family-focused debit card and money-management app designed to help children and teenagers learn how to handle money with guidance from their parents or guardians. Parents typically manage the account, set spending rules, and monitor activity, while children can use the card for approved purchases and learn practical habits such as budgeting, saving, and responsible spending.
How does the Till debit card work for children and parents?
A parent or guardian generally creates and manages the Till account, adds funds, and provides the child with a linked debit card. Depending on the available features and plan, parents may be able to review transactions, set controls, organize allowances, and send money. Children can then spend within the available balance, making the card a supervised alternative to carrying cash.
Are there fees, subscription costs, or spending limits with Till?
Before downloading or signing up, families should carefully review Till’s current pricing, because fees and plan details may change. Possible costs can include a monthly subscription, card-related charges, replacement fees, or other service expenses. Spending is normally limited by the account balance and any controls established by the parent, but transaction and withdrawal restrictions may also apply.
Is Till safe for children to use, and can parents monitor transactions?
Till is intended to provide a more controlled way for children to use money than an unrestricted adult bank account. Parents can generally view card activity and manage the child’s access through the app, although the exact monitoring and notification tools depend on the current version and account plan. Parents should still discuss online safety, protect login details, and review transactions regularly.
What should families check before downloading Till: Debit Card for Kids?
Families should confirm that Till is available in their country, check the supported age range, and verify whether a parent or guardian must meet specific identity or banking requirements. It is also important to read the latest terms, privacy policy, fee schedule, card delivery information, and supported payment features. Availability of functions can vary by location, device, and subscription plan.











